
Case Study Analysis of Using ETF Options for Directional Trading in the Memory Sector
Directional trading in the memory sector used to mean picking individual DRAM or NAND stocks and riding the cycles. Today, there is a cleaner, more structured way to express those views: options on thematic ETFs dedicated to memory and AI storage. These products wrap a complex, global supply chain into a single tradable instrument, and their option chains open the door to a wide range of strategies, from aggressive directional bets to more nuanced hedging and income approaches.
This post walks through a case study style analysis of using ETF options for directional trading in the memory sector. We will focus on an illustrative memory ETF, think through several trading scenarios, and explore what works, what breaks, and how to stay flexible. The goal is not to give rigid rules, but to tell a series of stories about how options can be used intelligently when the underlying theme is AI storage and computing power.
Setting The Stage: The Memory ETF As A Directional Vehicle
Imagine an ETF that tracks a global index of memory companies: DRAM and NAND manufacturers, controller designers, storage module suppliers, and select AI infrastructure players whose economics are tightly tied to memory cycles. In real markets, products like the Roundhill Memory ETF (ticker DRAM) already offer exactly this kind of exposure, with listed options that cover calls, puts, multiple strikes, and various expirations.
When you trade options on such an ETF, you are not simply speculating on one company’s earnings report. You are expressing a view on the broader memory cycle: pricing power, capacity expansions, supply disruptions, AI demand, and even geopolitics. The ETF acts as a basket that smooths idiosyncratic noise, while the options give you leverage and flexibility around direction and timing. This combination is ideal for case study analysis because it highlights both the appeal and the risk of thematic derivatives.
Case Study 1: A Bullish Momentum Phase And Long Calls
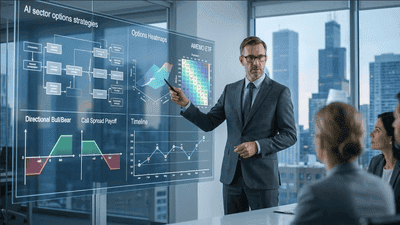
Our first case begins in a period of obvious momentum. Spot DRAM prices are climbing, NAND inventories are tightening, and AI infrastructure spending is visibly driving demand for high-bandwidth memory and fast storage. The memory ETF has already rallied, but the trader believes the cycle still has room to run.
Instead of buying the ETF outright, the trader chooses a long call strategy. They select out-of-the-money calls with a few months until expiration, aiming to capture a further upside move with limited capital at risk. The reasoning is straightforward:
- Directional conviction: The trader expects memory stocks to benefit from strong demand and positive sentiment.
- Capital efficiency: Calls offer leveraged exposure; if the ETF advances, the percentage gains on the option can be substantial relative to the premium paid.
- Defined downside: The maximum loss is the premium, which feels comfortable given the perceived strength of the cycle.
As the cycle unfolds, the ETF continues higher. The calls move deeper into the money, delta rises, and the trader experiences accelerating gains. This is the textbook bullish options case: using calls on a memory ETF to ride an uptrend driven by AI storage demand, without tying up a large amount of capital in the underlying.
Lessons From Case Study 1
The long call case illustrates several important points about directional trading in thematic ETFs:
- Trend alignment matters. Long calls work best when price, narrative, and fundamentals are moving in the same direction.
- Time horizon is crucial. Calls with too little time to expiration can be hurt by short-lived pullbacks or slow-moving cycles.
- Volatility cuts both ways. Elevated implied volatility can make calls expensive; gains must overcome both time decay and premium cost.
For memory sector traders, the takeaway is that long calls are powerful tools in clear, strong trends, especially when AI storage demand is visibly driving the story. They are less forgiving in choppy environments where cycles are unclear or policy risks loom.
Case Study 2: Bearish Phase And Protective Puts
Our second case shifts tone. Now the memory sector faces headwinds: oversupply fears, softer PC and smartphone shipments, or policy uncertainty affecting exports. The ETF has started to roll over from prior highs, and long-only investors in the memory theme are nervous but not ready to exit entirely.
One investor holds a sizable position in the ETF itself, perhaps as part of a broader AI infrastructure allocation. Rather than sell and potentially miss a rebound, they decide to use protective puts. They buy put options on the same memory ETF, with strikes near current price and expirations that cover the next few months of risk. Their logic:
- Directional concern: They see downside risk but do not want to abandon the theme.
- Portfolio protection: Puts act like insurance, limiting losses if the ETF falls further.
- Optionality: If the market stabilizes, the puts can be allowed to expire, preserving upside in the underlying ETF.
As the downturn extends, the ETF declines. The protective puts rise in value, offsetting losses in the underlying. The investor experiences a smoother equity curve, with the psychological comfort of having a defined floor. This use of ETF options for hedging is less glamorous than pure speculation, but it is fundamentally directional: the investor acknowledges meaningful risk in the memory sector and uses derivatives to manage it more gracefully.
Lessons From Case Study 2
Protective puts highlight a more defensive angle on directional trading:
- You can hold a thematic conviction while still trading direction via options; hedging is a directional act.
- Insurance has a cost. Frequent use of puts can erode returns in a persistent uptrend; timing and sizing matter.
- Psychology is part of the equation. Investors often value the psychological safety of protective structures as much as the mathematical payoff.
In memory and AI storage themes, where cycles can whipsaw and policy headlines arrive unpredictably, protective puts can be a way to stay engaged without being fully exposed to every downturn.
Case Study 3: Range-Bound Markets And Short Volatility
Not every phase is trending or collapsing. Sometimes the memory ETF gets stuck in a range. Prices oscillate as investors debate whether AI-driven demand is enough to offset cyclical softness in devices, and news flow alternates between optimism and caution. Options implied volatility remains elevated because traders still remember recent sharp moves, but realized price action is modest.
In this environment, a different kind of directional trader steps in: one who has a view that the memory ETF will not break out dramatically in either direction in the near term. They consider short volatility strategies using options, such as selling covered calls or put spreads:
- Covered calls: The trader owns the ETF and sells out-of-the-money calls, collecting premium while accepting limited upside if a surprise rally occurs.
- Put spreads: They sell a higher strike put and buy a lower strike put, expressing a view that the ETF won’t fall dramatically below the upper strike.
These strategies are directional in a different sense. The trader is betting that the memory sector’s next major move is “no move” — or at least, not one large enough to breach option strikes significantly. They profit if the ETF drifts or oscillates within a band and option premiums decay.
Lessons From Case Study 3
Range-bound directional trading via ETF options underscores:
- Direction can mean “sideways” as much as up or down; betting on a lack of extreme movement is still a directional view.
- Short volatility carries tail risk; sudden news about AI demand, export controls, or new capacity can break the range and hurt short option positions.
- Structures like covered calls and spreads allow for more controlled risk than naked option selling, but they still require careful monitoring.
In the memory sector, where cycle narratives can flip quickly, short volatility strategies need strong discipline and a plan for exits if the ETF starts to break out of its range.
Case Study 4: Leveraged ETF And Options – A Layered Bet
Some traders are drawn to more exotic combinations. Suppose there is a leveraged memory ETF that targets 2x daily exposure to the same underlying index, using swaps and other instruments. Now imagine pairing options on the non-leveraged memory ETF with positions in the leveraged product. This creates a layered directional structure: spot exposure is amplified, and options provide additional leverage or downside protection.
In one scenario, a trader is strongly bullish on the next leg of the AI storage cycle. They take a long position in the 2x memory ETF and also buy calls on the standard memory ETF. This is a pronounced directional bet:
- The leveraged ETF accelerates gains if the index rises.
- The long calls add convexity, potentially multiplying returns if the rally is large and sustained.
- Downside risk is substantial in the leveraged ETF, but limited in the calls.
This layered case is not for the faint-hearted. A sudden reversal or prolonged choppy period can erode the leveraged ETF’s value and leave the calls decaying. Nonetheless, it illustrates the creative ways traders can stack ETF and options exposures when they believe strongly in the memory sector’s direction.
Lessons From Case Study 4
Layered trades show the edge and the cliff of directional ETF option strategies:
- Leverage on leverage can produce outsized gains, but also magnifies the impact of being wrong on direction or timing.
- Understanding path dependency matters; daily rebalancing in leveraged products can create unexpected outcomes over longer horizons.
- Risk controls need to be explicit: predetermined exit levels, position limits, and scenario planning become non-negotiable.
In the context of AI storage and computing power, where cycles can be powerful but noisy, layered strategies are best suited to traders who can monitor positions closely and accept the full spectrum of outcomes.
Case Study 5: Event-Driven Directional Trading Around Memory Catalysts
Our final case focuses on catalysts. Memory sectors often experience discrete events: major earnings reports from leading DRAM or NAND producers, announcements of new fabs, regulatory news affecting AI chips, or high-profile IPOs of memory giants. These events can cause sharp, directional moves in the memory ETF.
A trader identifies an upcoming catalyst, such as a quarterly report from a key memory player or an AI infrastructure spending update. They expect the event to resolve a period of uncertainty, pushing the ETF either significantly higher or lower. Several strategies come into play:
- Directional calls or puts: If the trader has a strong view (for example, bullish on AI demand), they might buy calls ahead of the event.
- Straddles or strangles: If they have less certainty about direction but expect volatility, they might buy both calls and puts, betting that the magnitude of movement will justify the combined premium.
- Post-event entries: They may choose to wait for the initial reaction and then use options to express a second-phase directional view, such as fading an overreaction or riding a confirmed breakout.
This event-driven case ties ETF options directly to the narrative of AI storage and computing power. Each event reshapes expectations about future demand, pricing, and capacity, and the ETF becomes a canvas where those expectations are rapidly repriced. Options offer a way to stand at the edge of that repricing with defined risk and flexible payoff structures.
Lessons From Case Study 5
Event-driven trading highlights:
- Directional trading can be episodic, keyed to specific catalysts rather than continuous trends.
- Implied volatility often elevates before major events; strategy choice must account for how much of the move is already priced in.
- Post-event discipline is vital; options that were attractive pre-event can lose appeal quickly once the news is known.
In memory and AI infrastructure themes, where the headlines can be dramatic, event-driven options trading offers both opportunity and pressure. Decisions must balance conviction, data, and the clock.
Bringing The Case Studies Together: A Flexible Framework
Taken together, these case studies show that using ETF options for directional trading in the memory sector is not one thing; it is many things. Long calls, protective puts, short volatility, leveraged overlays, and event-driven strategies all inhabit the same landscape, but they respond to different market climates and different trader temperaments.
A flexible framework for directional trading in memory-focused ETFs might include:
- Matching strategies to regimes: trend-following calls in clear uptrends, protective puts in vulnerable phases, range strategies when cycles pause.
- Integrating fundamental and technical signals: using memory price and inventory data alongside chart-based support and resistance levels.
- Using risk tiers: treating layered and event-driven strategies as higher-risk, while protective and covered approaches occupy more conservative tiers.
This flexibility keeps directional trading from becoming rigid or monotonous. The same ETF and option chain can be read differently depending on where the memory cycle sits and what kind of risk a trader is willing to assume.
Conclusion: Direction, Options, And The Rhythm Of Memory
The memory sector sits at the heart of AI storage and computing power. Its cycles shape the economics of data centers, devices, and AI workloads. ETF options built on memory-themed products translate those cycles into tradable instruments, inviting traders and investors to express directional views with precision and creativity.
Case study analysis helps us see the variety in these expressions. Sometimes the story is straightforward bullish momentum, captured through long calls. Sometimes it is cautious protection, expressed via puts. Sometimes it is a sideways chapter, where short volatility structures make sense. And sometimes it is a high-stakes episode around a catalyst, where options become the tool of choice for navigating uncertainty.
In all cases, directional trading via memory ETF options asks the same underlying question: where do you think the rhythm of the cycle is headed, and how much are you prepared to stake on that belief? Answering that question honestly, and pairing it with strategies that match both market conditions and personal tolerance, is the real art behind the mechanics. The memory sector will continue to swing with AI’s evolution; ETF options ensure that those swings can be engaged not just with exposure, but with nuance.
You May Like

Narrowing Spread Between NAND Spot and Contract Prices in 2026 – A Signal
By 2026, one of the most watched metrics in the NAND flash market has started to shift in a subtle but meaningful way: the spread between spot prices and long‑term contract prices is narrowing. For casual observers, this may look like just another incremental change in a notoriously volatile industry. For memory makers, module houses, device OEMs, and data center buyers, however, a tightening gap between spot and contract prices is a signal—a reflection of evolving supply–demand balance, risk perceptions, and strategic behavior on both sides of the market.

Price Divergence Trading Strategies Between NAND Flash and DRAM ETFs
NAND flash and DRAM sit at the core of AI storage and computing power. Both are memory, but they are not the same business. DRAM is main memory—fast, volatile, and central to high‑bandwidth workloads like AI training and inference. NAND is non‑volatile storage—slower than DRAM, but crucial to persistent data and large‑scale object storage. The cycles that drive their pricing and margins overlap, yet they often diverge. That divergence is where trading strategies between NAND and DRAM ETFs become interesting.

China’s HBM Localization Progress: The Catch-Up Pace of CXMT and XMC
China’s drive to localize advanced memory technologies has accelerated over the past several years. High-Bandwidth Memory (HBM) sits near the center of that strategy because it is integral to AI accelerators, high-performance computing (HPC) and other strategic compute platforms. Two domestic players—ChangXin Memory Technologies (CXMT) and XMC (Xianghui Memory, commonly referred to as XMC)—have become focal points in assessing how quickly China can close the gap with international incumbents on HBM die, stacking, and packaging.

Thermal Simulation Challenges and Solutions in 3DIC AI Chip Design
As AI workloads push chips to deliver ever higher compute density, designers are increasingly turning to three‑dimensional integration (3DIC) to stack dies vertically and pack more functionality into limited footprints. While 3DIC architectures unlock significant performance and bandwidth advantages, they also introduce complex thermal behaviors that are far harder to predict and manage than in traditional 2D layouts.

An Attempt at Compiling a Memory+Compute Fusion Thematic Index – A Dual-Track Framework
Most AI investors talk about “compute” as if it were the whole story: GPUs, accelerators, chips, cores. But every one of those cores needs somewhere to read from and write to. Memory and storage define how wide the data highway really is. In practice, AI performance is a fusion of compute and memory, not a solo act. So why do so many indices and ETFs separate them into different silos—one for semiconductors, one for memory, one for data centers—when the actual workloads keep blending them?

Surging Demand for Laser Drilling and Plasma Dicing Equipment in Advanced Packaging
Advanced packaging has become one of the semiconductor industry’s most important growth engines, and it is now pulling a surprising set of process tools into the spotlight. Among the most in-demand are laser drilling and plasma dicing equipment. These machines sit close to the heart of heterogeneous integration, fan-out packaging, wafer thinning, TSV formation, glass substrate processing, and other advanced flows where precision, yield, and throughput matter enormously. As packaging moves from a back-end afterthought to a strategic platform, the equipment used to shape, open, and separate materials has become just as important as the dies themselves.

D2D Interface Bandwidth and Latency Comparison in Chiplet Architectures
Chiplet architecture has turned the package into a real performance battleground. Once multiple dies are placed side by side or stacked within the same advanced package, the quality of the die-to-die, or D2D, interface becomes one of the most important determinants of system behavior. Bandwidth is no longer a nice-to-have metric, and latency is no longer a small implementation detail. Together, they shape whether a chiplet system feels nearly monolithic or frustratingly fragmented.

Stock Selection Logic and Alpha Validation of ESG-Themed Semi ETFs
Semiconductor themed ETFs are no longer just about growth and cycles. A growing subset now layers environmental, social, and governance (ESG) criteria on top of traditional sector exposure. These ESG semi ETFs promise two things at once: access to one of the market’s most powerful secular themes, and alignment with sustainability and governance standards. The pitch is appealing, but it raises two hard questions. First, how exactly are these stocks being selected? Second, does the ESG overlay help, hurt, or leave alpha unchanged?